

There is no simple right or wrong answer when a major hospitality property faces changing demand, rising operating costs, expensive renovation needs, and an uncertain economic outlook . Owners must decide where to place capital based on the facts available today while trying to anticipate what customers, investors, lenders, and the market may demand tomorrow. Atlantic City is now offering an interesting example of two major hospitality properties taking very different paths. Ocean Casino Resort is investing $14 million to expand The Cove, its high limit slot area, after identifying strong demand for a premium gaming experience. At the same time, the Sheraton Atlantic City Convention Center Hotel is pursuing a proposed $100 million redevelopment that would reduce its hotel room inventory and introduce age restricted housing as part of a new mixed use model. These are not simply two construction projects. They are two very different approaches to improving the long term performance of large existing assets. Ocean is choosing to invest more heavily in an experience that management believes is already working. The Sheraton is considering a change in use because its owner says the hotel, at its present 502 room size, cannot be sustained by convention demand alone. Both decisions are based on the same fundamental question. How can an owner create the strongest possible future from the property they already own? Ocean is expanding an area of demand Ocean Casino Resort’s decision is built around a relatively straightforward idea. If a particular part of the property is producing strong demand, the owner may decide that it deserves more space, more capital, and a better customer experience. The Cove is currently approximately 7,450 square feet. Ocean plans to expand it to 11,935 square feet, an increase of nearly 60 percent. The expanded Cove is expected to include more than 192 slot machines and is scheduled to open in early 2027. The project is not simply about adding machines. Ocean has said the redesigned space will include lounge seating, specialized cocktail service, dedicated restrooms, cashier booths, and a more elevated high limit environment. The company says the expansion is a response to strong demand for high end slots. From a commercial real estate perspective, that is an important distinction. Ocean is not adding another hotel tower. It is not adding hundreds of guest rooms. It is not acquiring another casino property. It is looking inside its existing resort and directing capital toward a particular experience that management believes can generate more revenue and provide a stronger guest experience. This is a lesson in revenue per square foot. Not every part of a hotel, casino, shopping center, restaurant, apartment complex, or mixed use property produces the same return. Some spaces have stronger customer traffic. Some support premium pricing. Some create repeat business. Some have demand that exceeds the space currently available. For Ocean, The Cove appears to be one of those spaces. The company is making a targeted investment in an area of the resort where it sees the opportunity to increase capacity while also increasing the level of service and comfort offered to its customers. The Sheraton is considering a different use mix The Sheraton Atlantic City Convention Center Hotel faces a different set of circumstances. The hotel has 502 rooms and is directly connected to the Atlantic City Convention Center. That connection gives the property importance beyond its own four walls. It is part of the lodging infrastructure Atlantic City needs to attract conventions, meetings, business travelers, exhibitors, and multiday events. But strategic importance does not automatically make an asset financially sustainable. The Sheraton’s owner has argued that the property cannot be supported by convention demand alone at its current size. The proposed redevelopment would therefore change the building’s business model. The plan calls for an approximately $100 million redevelopment. It would convert 130 hotel rooms into age restricted apartments and renovate 252 hotel rooms, creating a smaller hotel component alongside residential use. The central idea is that the residential component could create a more dependable, recurring income stream, while the renovated hotel would continue to provide convention related lodging. This is not simply a conversion story. It is an adaptive reuse strategy designed to reduce the property’s dependence on one revenue source. A hotel depends on room demand, rates, group bookings, leisure travel, convention activity, labor costs, operating expenses, competition, and economic conditions. A residential component, if successfully developed and leased, may offer a different type of income stability. Of course, the proposal also raises an important question for Atlantic City. If the Sheraton’s room count is reduced, will Atlantic City still have enough conveniently located hotel rooms to compete for larger conventions? That is a fair question. The Sheraton is directly connected to the Convention Center. Those rooms have value to meeting planners and event organizers because they provide convenience for attendees, speakers, exhibitors, and staff. Reducing the hotel inventory could make it harder to offer room blocks close to the Convention Center. At the same time, supporters of the redevelopment can make an equally reasonable argument. If the existing 502 room hotel cannot be sustained financially, preserving a smaller and renovated hotel may be better than allowing the entire property to close or continue to decline. The Sheraton’s proposal reportedly depends on financing support, including $79 million in Aspire tax credits. The Aspire program is intended to provide gap financing for projects that may not be economically feasible without assistance. The proposal therefore involves more than a building redesign. It involves capital, public policy, convention economics, housing demand, and the long term future of one of Atlantic City’s important hospitality assets. Two different strategies, one shared goal Ocean Casino Resort and the Sheraton Atlantic City Convention Center Hotel are taking very different approaches, but both ownership groups appear to be pursuing the same goal. They are trying to optimize the best possible outcome from the facts available today and their expectations for tomorrow. Ocean is investing in a premium customer experience that management believes has demand now and may generate even more revenue with greater capacity and better service. The Sheraton is proposing a mixed use model because its owner believes that the existing hotel format no longer provides enough dependable income on its own. One strategy is based on expanding what is working. The other is based on adapting what may no longer work at its original scale. Neither decision is guaranteed. Ocean will need to show that its expanded Cove produces enough additional revenue, premium customer spending, and guest loyalty to justify the $14 million investment. The Sheraton will need to show that a smaller hotel and age restricted residential component can create a stronger, more stable asset while preserving a meaningful role in Atlantic City’s convention business. That is why this comparison is so interesting. It is not a matter of one property making a correct decision and the other making a mistake. It is a reminder that commercial real estate decisions are often made under uncertainty. Owners must evaluate current operating data, customer demand, construction costs, market competition, financing conditions, and future risk before deciding where to allocate capital. The larger real estate lesson For property owners, investors, and developers, the broader lesson is that growth does not always mean more buildings, more rooms, or more square footage. Sometimes the best investment is to expand the part of the asset that is already generating the strongest return. That could mean premium gaming, food and beverage, luxury suites, meeting space, outdoor amenities, medical space, entertainment, fitness, marina services, retail, or another high demand use. At other times, the most responsible decision may be to recognize that part of the property is no longer generating enough income in its existing form. In that case, the owner may need to consider a different mix of uses, including residential, senior housing, extended stay, office, medical, education, or entertainment. The important question is not simply, “What should we build next?” The more useful question may be: Which part of the property we already own has the best chance to create more value, and which part needs a new purpose? Ocean and the Sheraton are giving Atlantic City a real time lesson in two possible answers. What do you think? When a large hospitality property faces changing demand, is the stronger strategy to invest more heavily in the part of the asset that is already performing well? Or is it better to reduce dependence on one revenue source and create a more diversified use mix, even if that means changing part of the property’s original purpose? There may not be one universal answer. The right decision depends on the asset, its location, its customer base, the owner’s financial position, available financing, renovation costs, local demand, and the risks of an uncertain economy. But Ocean Casino Resort and the Sheraton Atlantic City Convention Center Hotel are offering Atlantic City two visible, very different paths forward. Sources & References: NJBIZ and Atlantic City Market.
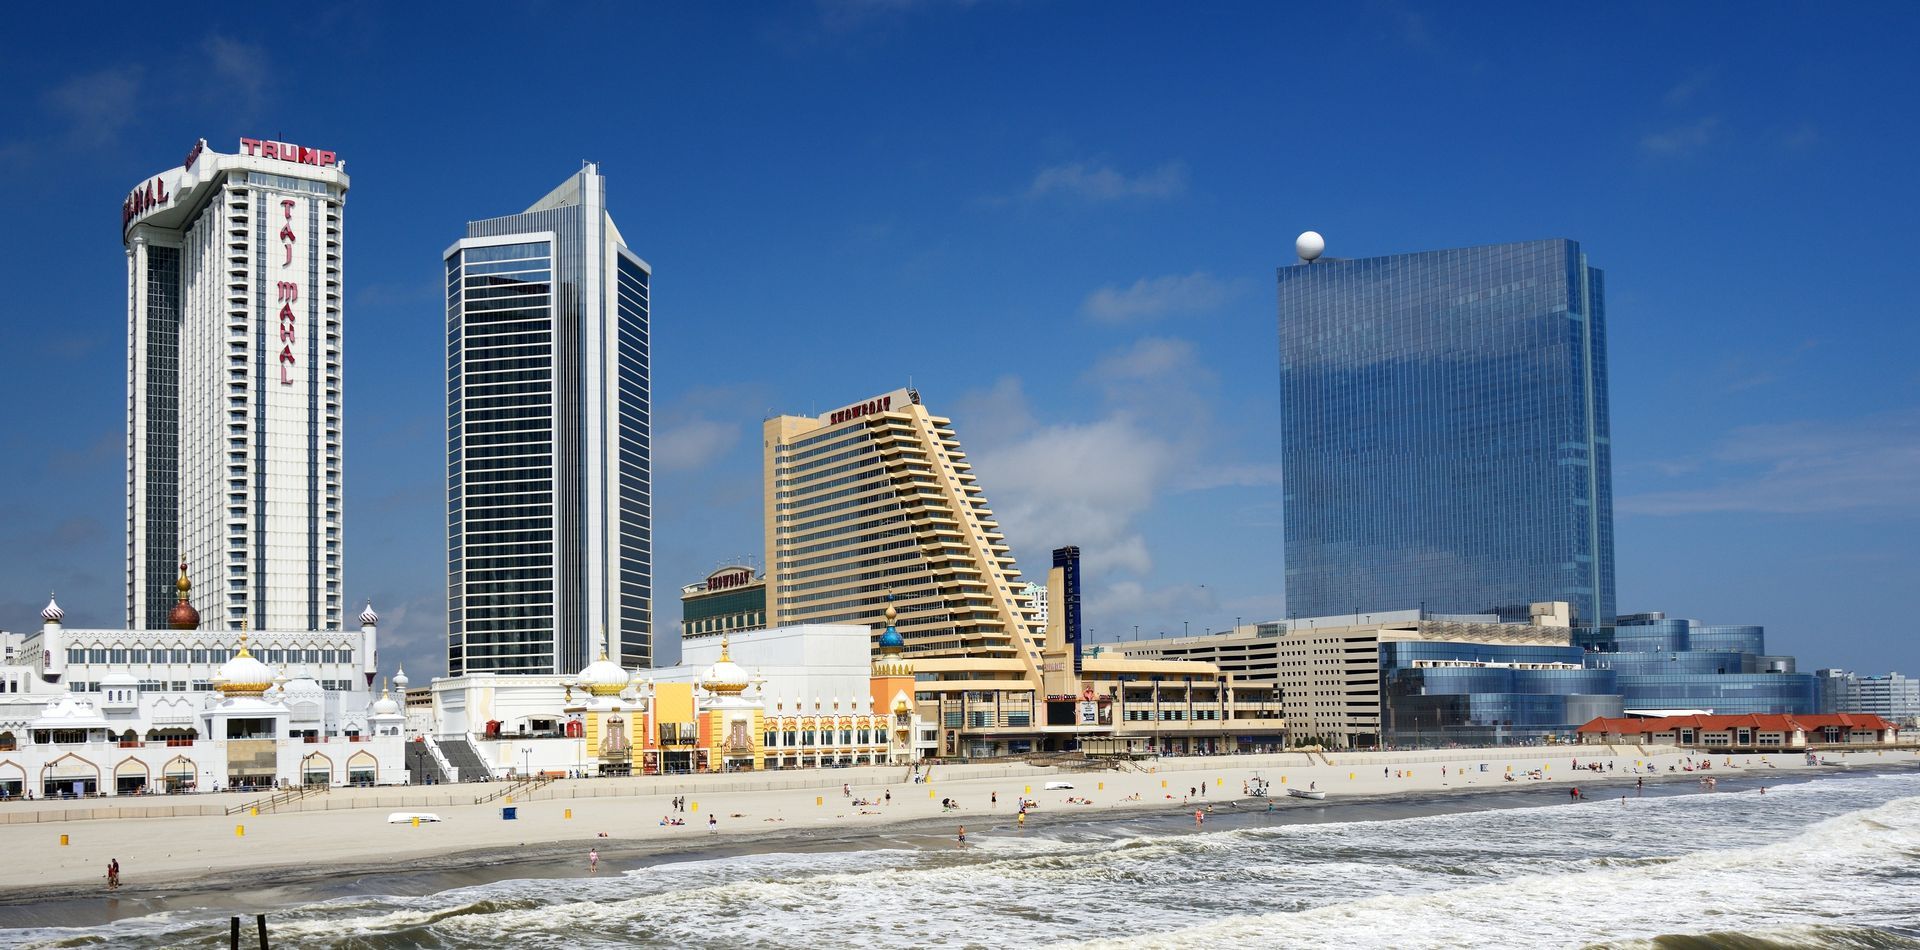
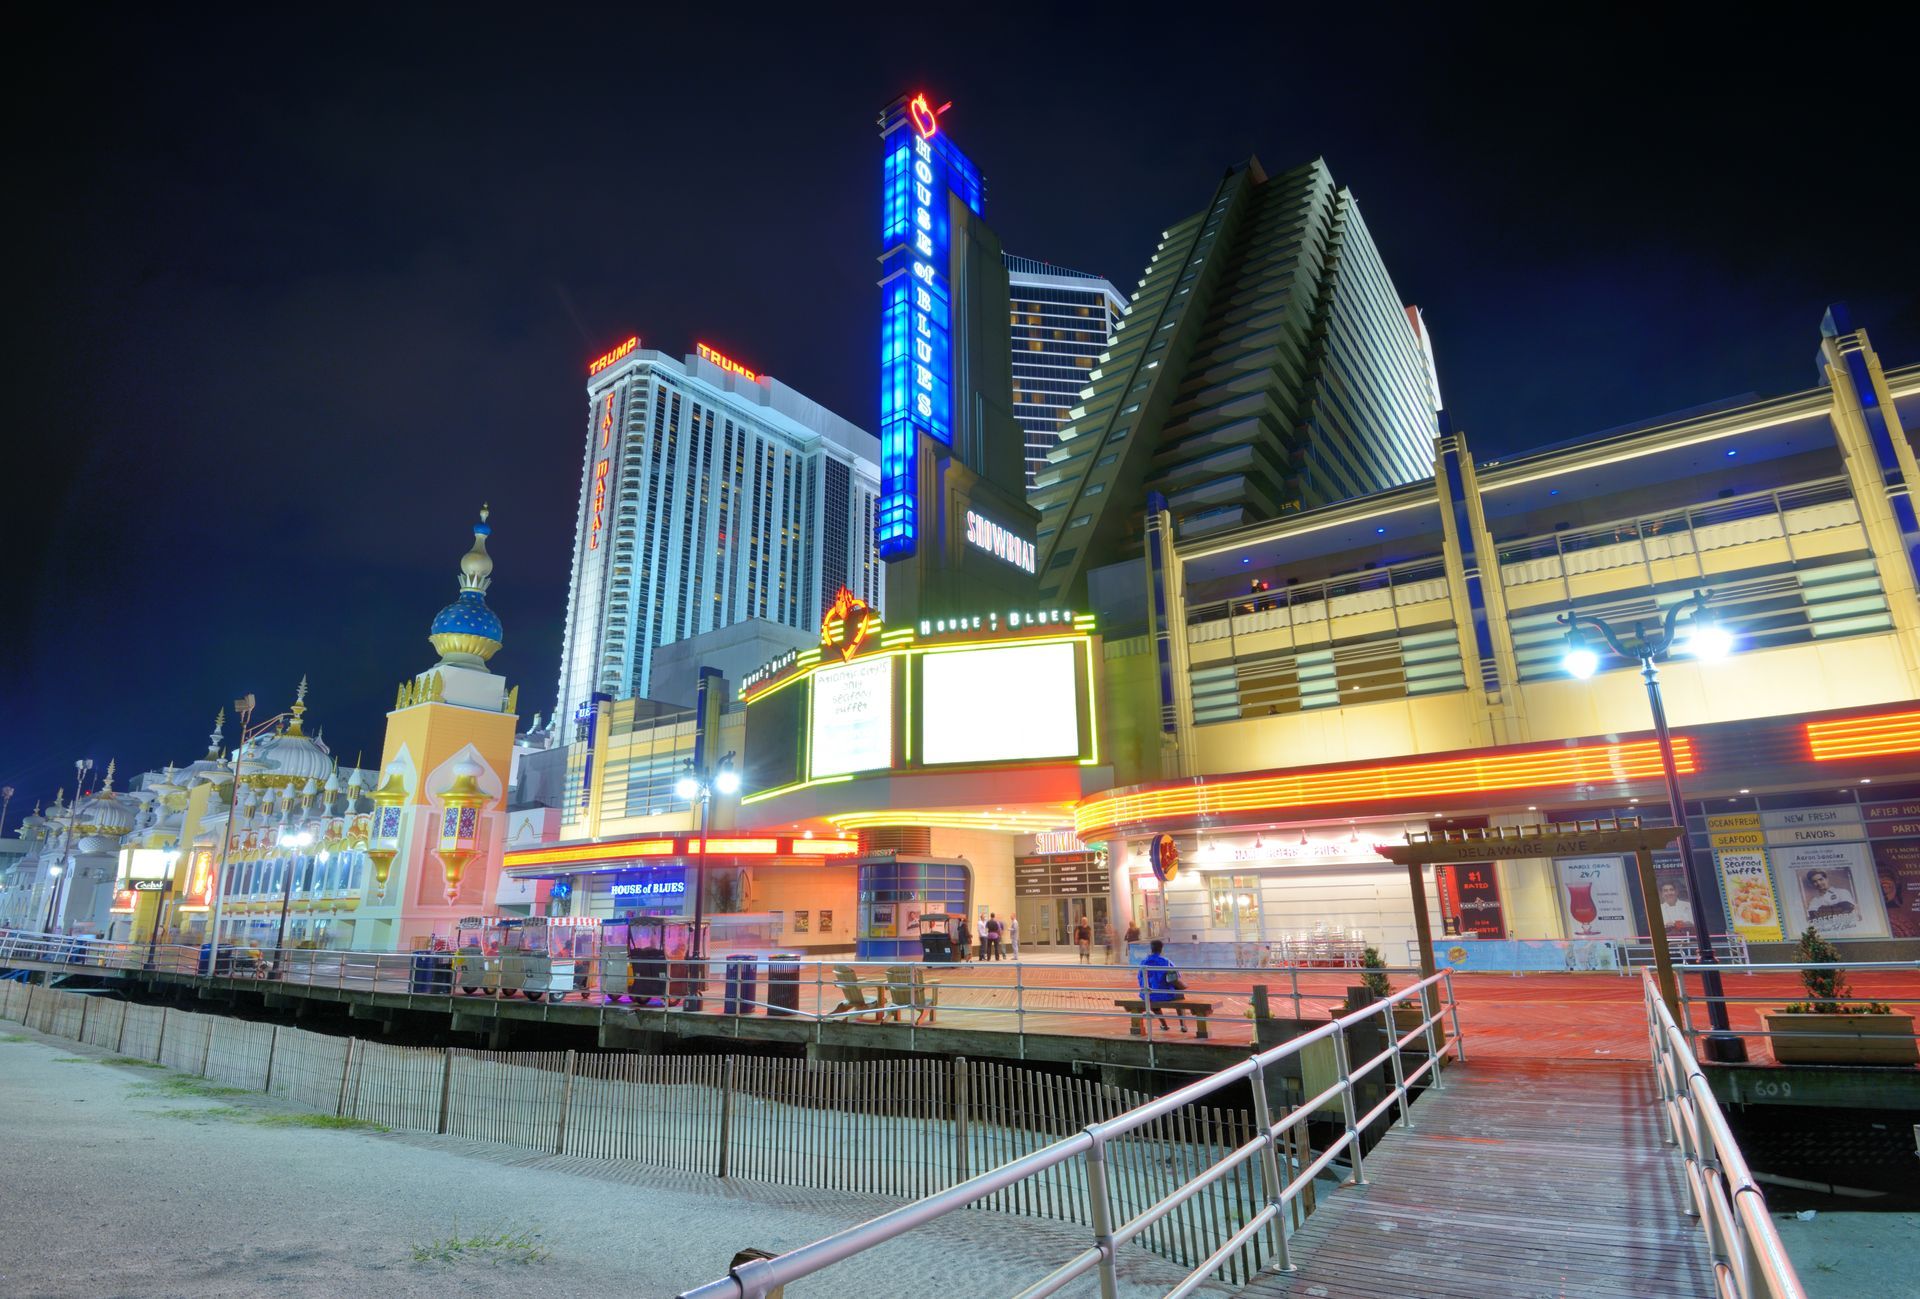
Atlantic City could lose one of its most important convention hotels unless a proposed $100 million redevelopment can turn an aging 502 room property into a more sustainable mixed use asset. The Sheraton Atlantic City Convention Center Hotel is not simply another hotel in the city. Its direct connection to the Atlantic City Convention Center makes it an important part of Atlantic City’s ability to attract conventions, meetings, business travelers, and multiday events. However, the hotel now faces a challenge that is becoming increasingly common across the country. It is an older, large hospitality asset that still holds strategic value, but may no longer be financially sustainable in the exact form in which it was built. The Sheraton contains 502 hotel rooms. Ownership has argued that Atlantic City does not consistently generate enough large, multiday conventions to support a convention hotel of that size. The property also reportedly requires substantial renovation and capital investment. Without a major overhaul, ownership has warned that the hotel could close and may risk losing its Marriott brand affiliation.The proposed answer is not to demolish the building or convert the entire hotel to apartments. Instead, ownership is seeking to create a new model for the property. A Plan to Preserve Part of the Hotel The proposed redevelopment is estimated at approximately $100 million. The plan would retain and renovate 252 hotel rooms while converting another part of the building into 130 age restricted residential units. Renovations are also planned for the first and second floors, common areas, exterior amenities, and pedestrian access. A new pedestrian canopy is proposed, and Tun Tavern would remain part of the property. The residential portion is not being positioned as a traditional assisted living facility. It is described as upscale living for residents age 55 and older, with amenities that may include a fitness center, golf simulator, indoor pool, and hot tub. The approved residential plan also includes 26 affordable units. This distinction is important. The proposal is not simply removing hotel rooms from the market. It is attempting to preserve a modernized convention hotel while bringing a more consistent residential presence into the building. In effect, the developer is asking a larger question. Can a reduced hotel inventory, supported by a residential component, produce a stronger long term outcome than maintaining a 502 room hotel that may not have enough reliable demand to justify its cost structure? Why a 502 Room Hotel Is Different A large convention hotel is expensive to operate. It requires staffing, maintenance, utilities, housekeeping, sales and marketing, food and beverage operations, reservations systems, insurance, brand compliance, and ongoing renovation. A hotel with 502 rooms needs meaningful occupancy in order to support those costs. It performs best when the adjacent convention center produces large groups that stay for several nights and fill significant blocks of rooms. That business model works well when convention demand is steady. It becomes difficult when large events are inconsistent, when visitors stay for shorter periods, or when the local market has more hotel rooms than it can support throughout the year. The hotel’s location beside the Atlantic City Convention Center remains a major advantage. Few local properties can offer that same direct connection. However, location alone does not eliminate the need for capital investment or guarantee that 502 rooms can be filled often enough to sustain the asset. The Sheraton proposal recognizes that reality. Rather than treating the hotel as a failed property, the redevelopment attempts to preserve the portion of the business that still matters to Atlantic City’s convention economy. At the same time, it would reduce the hotel inventory and add residential units that could create a separate, year round source of activity and revenue. Atlantic City Is Not Alone The Sheraton’s challenge is part of a wider shift taking place in the hospitality industry. Large hotels across the United States are not all struggling in the same way. Many are receiving significant investment because they are located in strong convention, tourism, business, entertainment, and leisure markets. Others are being renovated, repositioned, converted, or redeveloped because the original business model no longer fits current demand. The difference often comes down to location, demand, condition, brand strength, and access to capital. Hilton Anaheim, one of the country’s largest convention oriented hotels, completed a major renovation of its 1,500 guest rooms and more than 170,000 square feet of indoor and outdoor meeting space. The work upgraded rooms, public areas, technology, and event capabilities in a market that continues to compete aggressively for group travel and large conventions. Other major hospitality investments include a $100 million multiyear transformation at the Hyatt Regency Hill Country Resort and Villas in Texas, a $65 million renovation at Boston’s Omni Parker House, and a $240 million renovation at the Mauna Kea Beach Hotel in Hawaii. These projects show that owners are still making large capital commitments where they see long term demand and a strong competitive position. The message is clear. The hospitality industry is not standing still. Hotels that remain competitive are investing in modern guest rooms, flexible meeting spaces, updated technology, improved restaurants and bars, outdoor amenities, wellness offerings, and experiences that give visitors a reason to choose one property over another. For older hotels, the cost of doing nothing can become more expensive than the cost of repositioning. The New Competition for Convention Business Convention hotels do not compete only with the hotel next door. They compete with entire destinations. A group considering Atlantic City may also be looking at Philadelphia, Baltimore, Washington, D.C., Boston, Nashville, Orlando, Las Vegas, Dallas, Houston, San Diego, and other convention markets. Those cities are not only competing for visitors. They are competing for the meetings, conventions, sporting events, corporate gatherings, and entertainment related travel that fill hotel rooms during the week and throughout the year. Many cities are responding with major investments in their convention districts. Las Vegas is completing a $600 million renovation of its convention center. Los Angeles is moving forward with a convention center redevelopment reported at nearly $2 billion. Dallas is advancing plans to reconstruct and expand the Kay Bailey Hutchison Convention Center, with costs reported in the range of $3.3 billion to $3.5 billion. Houston is pursuing a major expansion and redevelopment of the convention center district around the George R. Brown Convention Center, with reported investment ranging from $1.4 billion to $2 billion. Miami Beach completed a $640 million convention center renovation and is moving forward with an 800 room Grand Hyatt headquarters hotel. Fort Lauderdale has added a new Omni headquarters hotel near its expanding convention center as part of a larger waterfront redevelopment strategy. These investments show how cities increasingly view convention centers, hotels, restaurants, retail, public spaces, transportation, and entertainment as one connected economic-development ecosystem. Atlantic City has advantages that other convention destinations cannot easily replicate. It has a beach, a nationally recognized casino market, entertainment venues, restaurants, retail, and a hotel base that can serve both leisure and group visitors. Still, Atlantic City must compete for group business in an environment where planners want modern hotels, dependable room blocks, quality meeting space, convenient transportation, and walkable attractions. The Sheraton’s future therefore matters beyond the property itself. A modernized and sustainable hotel connected to the convention center could strengthen Atlantic City’s ability to compete. A closure could create a gap in the city’s convention lodging infrastructure. Adaptive Reuse Is Changing…Adaptive reuse is often described as a complete change of use. An old office building becomes apartments. A hotel becomes workforce housing. A former retail center becomes medical space, industrial space, self storage, or mixed use development. The Sheraton proposal is different. It is not a full conversion. It is a strategic rebalancing of an existing asset. The hotel would remain a hotel, but with fewer rooms. The proposed residences would introduce a second use and a more stable year round presence. That could help support the building’s financial model while preserving its role in the convention economy. This may become a more common approach for older hotels across the country. Some assets will be renovated and remain entirely hospitality focused. Others will be converted completely to residential, student housing, workforce housing, affordable housing, or extended stay lodging. Still others may be repositioned as mixed use properties that combine hotel rooms with residences, retail, restaurants, offices, entertainment, medical space, or other complementary uses. The future of hospitality is likely to be more selective and more flexible. Hotel owners will continue to invest in markets where travel demand is strong and growth is clear. But in markets where demand has changed, owners may need to rethink the mix of uses within a building rather than simply adding more rooms or continuing with the same operating model. The Financing Question The Sheraton proposal has received key local approvals. The Casino Reinvestment Development Authority approved the land use request, and Atlantic City approved a 30 year PILOT agreement for the project. However, the project still depends on putting together its full financing package. Ownership is seeking assistance through New Jersey’s Aspire Program and has requested approximately $79 million in tax credits. The owner has indicated that private financing is close, but that Aspire support is needed to close the remaining financial gap. As of late September, the requested tax credits had not been approved. This is where the project becomes more than a real estate story. It becomes a public policy and economic development question. Supporters may argue that public incentives are justified if they help preserve a major hotel, protect jobs, maintain convention related lodging, revitalize an aging property, and prevent a strategically located building from declining. Others may question whether a privately owned hotel and residential project should receive substantial public assistance. Both perspectives deserve consideration. The reality is that large redevelopment projects often require complicated capital stacks. Private equity and conventional debt may not be enough when a project includes major renovation costs, aging infrastructure, uncertain revenue, mixed uses, and a long timeline for returns. PILOT agreements, tax credits, public infrastructure support, and other incentives are often used to make redevelopment feasible. Whether the Sheraton receives Aspire funding will likely determine whether this plan moves forward. What the Future May Look Like The American Hotel and Lodging Association projects that hotel guest spending could reach nearly $805 billion in 2026, a 1.7 percent increase from 2025. Major events, including the FIFA World Cup and America250 celebrations, are expected to support travel demand in selected markets. That is encouraging for the hotel industry, but national numbers do not tell the whole story. Not every hotel will benefit equally. Properties with modern rooms, strong brands, good locations, access to capital, and clear demand drivers will likely be best positioned to attract investment and maintain pricing power. Older hotels with deferred maintenance, inconsistent occupancy, excess room inventory, and limited access to renovation capital may face much more difficult decisions. For these properties, the future may not be a choice between success and failure. It may be a choice between strategic reinvestment, creative repositioning, partial conversion, or eventual obsolescence. The Sheraton Atlantic City Convention Center Hotel is now facing that decision in real time. A Defining Test for Atlantic City The proposed redevelopment is about more than 130 age restricted residential units. It is about whether Atlantic City can retain an important convention hotel by making it better suited to current market conditions. It is about whether an older hospitality asset can be modernized and rebalanced before deferred maintenance and financial pressure become too great. It is also about whether public incentives can help preserve a building that serves a broader economic role for the city. The outcome will be worth watching. If the project succeeds, the Sheraton could become an example of how a large hotel can evolve without abandoning its core purpose. It could retain a meaningful role in Atlantic City’s convention market while adding a residential component that makes the property more sustainable. If it does not move forward, it will serve as a warning about the challenges facing older hotels that are strategically important but financially difficult to renovate. For Atlantic City, the real question is not whether some hotel rooms should become residences. The $100 million question is whether a smarter mix of hotel and residential uses can secure the future of one of the city’s most important convention related properties Sources and references: New Jersey Casino Reinvestment Development Authority (NJCRDA), PR Newswire, Shore Local Newsmagazine, Meetings Today, Skift, Pollstar, WHYY, and the American Hotel & Lodging Association (AHLA)
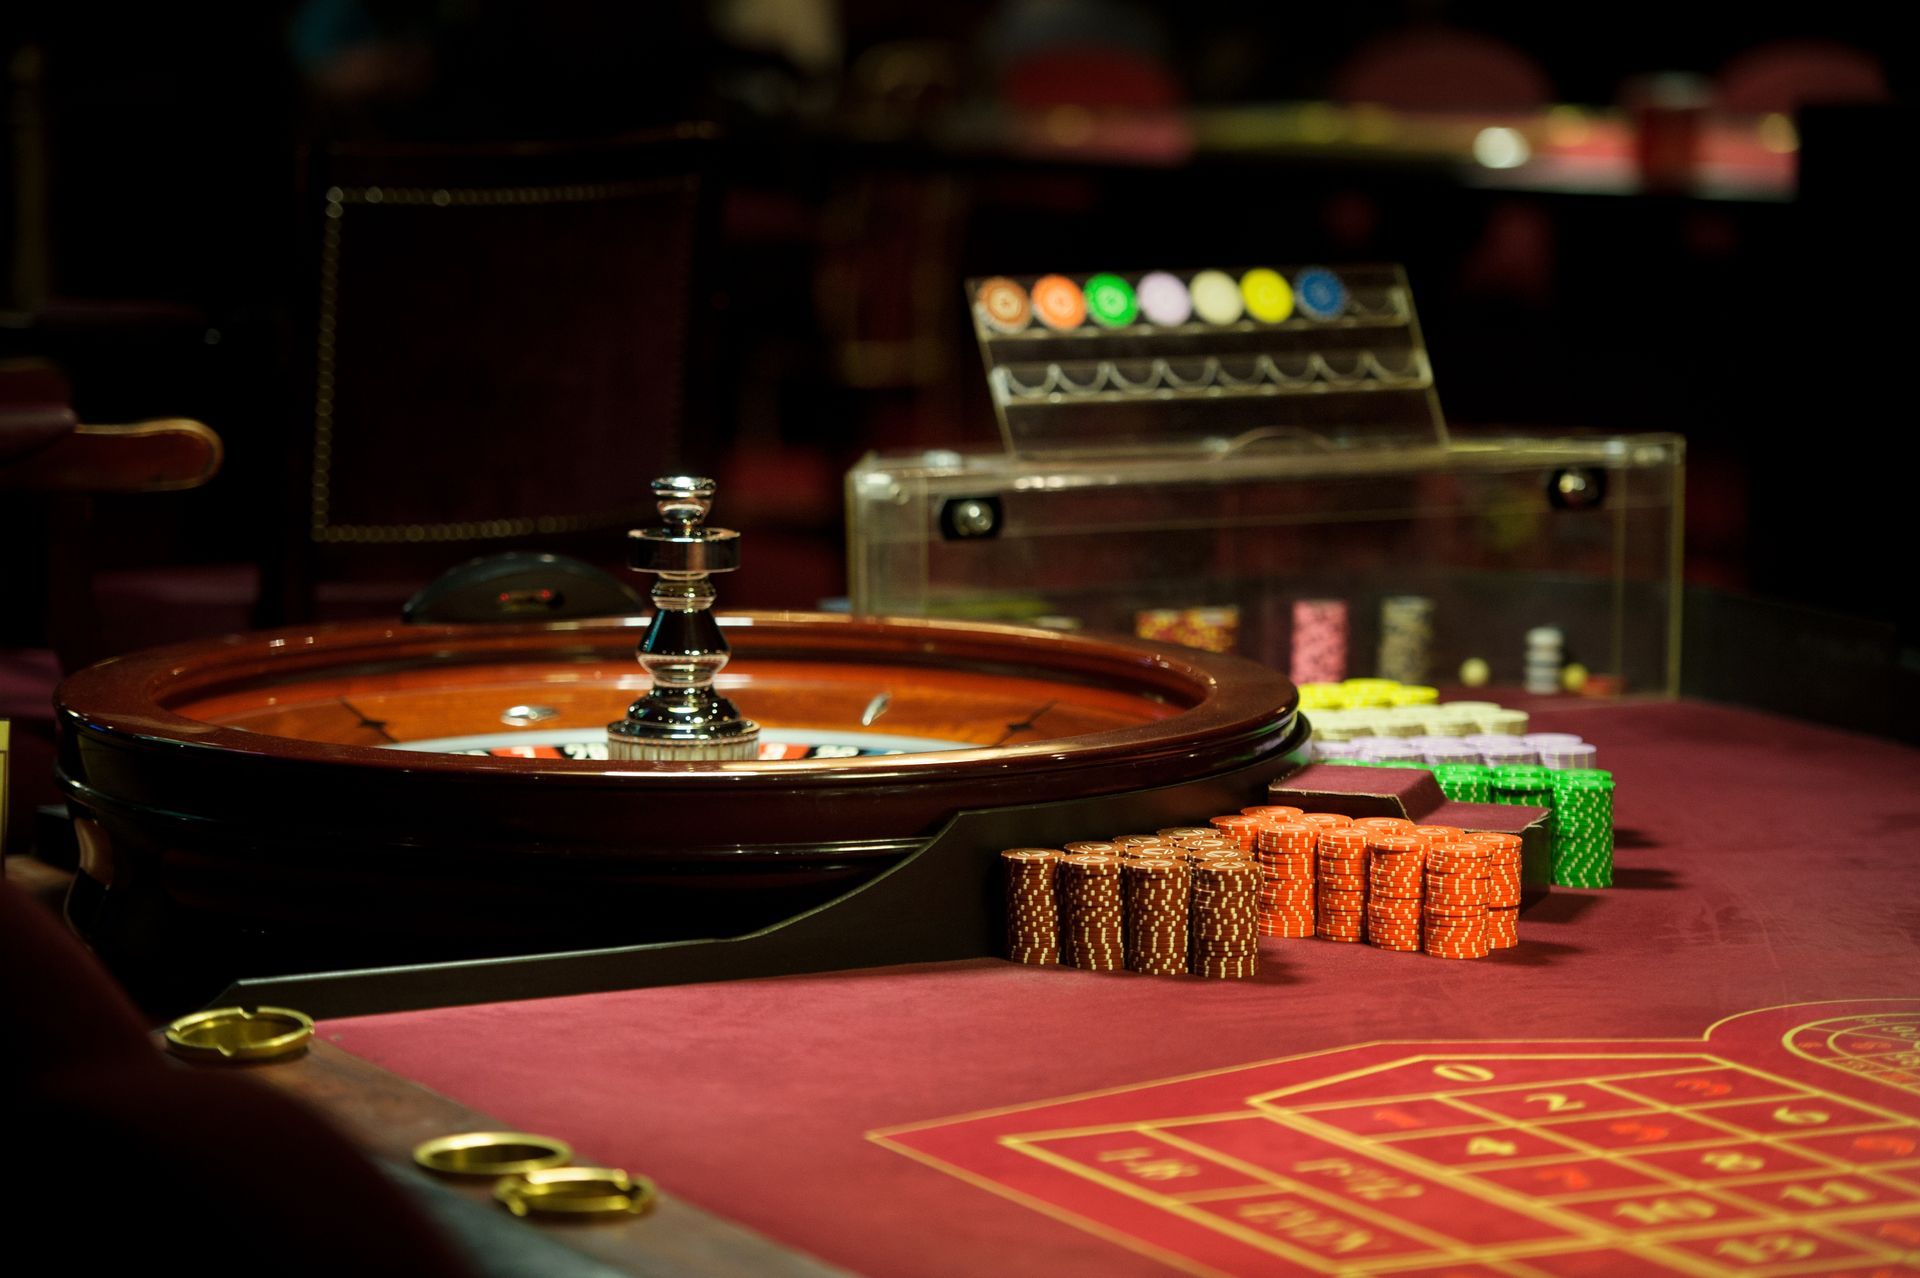
When a major hospitality property announces a $14 million investment, it is easy to assume the owner is preparing to build another tower, add hundreds of rooms, acquire more land, or create an entirely new attraction. That is not what Ocean Casino Resort is doing. Ocean recently announced plans to invest $14 million in the transformation and expansion of The Cove, its high limit slot area. The existing space, which is approximately 7,450 square feet, will expand to 11,935 square feet. That represents growth of nearly 60 percent. The redesigned area is expected to include more than 192 slot machines and is scheduled to open in early 2027. At first glance, this may look like another Atlantic City casino expansion story. But from a commercial real estate and hospitality perspective, it is something more useful to study. Ocean is not simply adding more machines. It is directing capital toward a specific part of an existing asset where management says demand is already strong. The company has said the project is being developed in response to demand for high end slot gaming. That detail may be more important than the $14 million price tag. An investment guided by demand The word “bet” would be easy to use when discussing a casino project, but it would not accurately describe what Ocean appears to be doing. A bet suggests speculation. Ocean’s project appears to be a targeted capital allocation decision based on the performance and demand it sees within its existing resort. The company is taking space that is already devoted to a premium gaming experience and expanding it because management believes that demand exceeds the current capacity of the area. That is a familiar commercial real estate decision. An owner studies a property, identifies the parts of the building where customers are spending money, recognizes where demand is strongest, and determines whether additional capital can create a stronger return. The question is not always whether to buy another building. Sometimes the more important question is this: Which part of the property I already own has the greatest potential to produce more income? For Ocean, management appears to believe that The Cove is one of those areas. Not all square feet are equal One of the most important lessons in commercial real estate is that not every square foot in a property produces the same return. A hotel may have a restaurant that underperforms while its rooftop bar is consistently full. A shopping center may have an older retail space that struggles while medical, fitness, food, and service oriented tenants attract regular traffic. An apartment building may find that premium units, reserved parking, outdoor space, or a well designed coworking lounge command far more value than a large but seldom used amenity room. The square footage may be the same. The revenue potential is not. Ocean’s expansion is a useful example of revenue per square foot analysis. The company is not simply increasing the size of its resort. It is increasing the size of a particular revenue producing experience within the resort. The new Cove will not only have a larger gaming footprint. Ocean has also announced lounge seating, specialized cocktail service, dedicated restrooms, and cashier booths. The space is being positioned as a more elevated, luxury oriented environment. That is significant because hospitality revenue is rarely created by square footage alone. Revenue is influenced by the guest experience, the quality of service, the length of time a customer remains on the property, the convenience of the space, the perceived exclusivity of the setting, and the likelihood that a guest will return. Ocean is investing in capacity, but it is also investing in the environment around that capacity. The value of a premium experience It would be too simple to say Ocean is merely adding slot machines. The project is designed to create a more complete high limit experience. Guests will have access to seating, dedicated beverage service, dedicated restrooms, and cashier services that reduce friction and provide a greater sense of comfort and privacy. This is the kind of decision that applies well beyond a casino. A luxury multifamily property may invest in a better lobby, a private resident lounge, concierge services, a fitness facility, reserved parking, or upgraded outdoor space. A hotel may decide its best return comes from premium suites, a high quality lobby bar, meeting space, a spa, or an upgraded pool experience. A retail center may improve outdoor dining, pedestrian access, parking, signage, landscaping, and gathering areas because those changes can strengthen both tenant sales and customer loyalty. In each case, the owner is not just renovating a space.The owner is trying to influence customer behavior. A stronger experience can encourage guests to remain longer, spend more, return more often, and view the property as different from competing alternatives. Atlantic City context matters Ocean’s decision is also occurring within a competitive Atlantic City gaming market where every operator must carefully evaluate where capital will produce the best return. Atlantic City’s nine casinos generated approximately $294.9 million in casino win from slot machines and table games in August 2026. Slot machine revenue accounted for approximately $222.4 million of that total. Those figures matter because they show that slot play remains a major component of Atlantic City’s physical casino business, even as online gaming continues to grow. Ocean Casino Resort has also been one of the few Atlantic City properties to remain ahead in year to date land based gaming revenue during 2026. Through August, Ocean’s casino win from slots and table games was approximately $329.9 million, an increase of 5.4 percent from the same point a year earlier. No monthly or year to date figure can guarantee that a new investment will succeed. Every capital improvement must ultimately justify itself through measurable operating performance. Still, the available information suggests that Ocean is not expanding an area at random. It is investing in a major revenue category and targeting a premium customer segment that management says is showing strong demand. The larger lesson for owners For commercial real estate owners, Ocean’s announcement is a reminder to look closely at the asset already under control. Before assuming that growth requires another purchase, another building, or another development site, it may be worth asking a few practical questions. Where is demand strongest inside the property? Which spaces produce the highest revenue per square foot? Which customer groups are already paying for a higher level of service, convenience, privacy, or quality? Which areas are constrained by their existing size, layout, or operating model? What investment could increase revenue without requiring an entirely new acquisition? Those questions apply to a casino resort, but they also apply to hotels, restaurants, shopping centers, apartment communities, office properties, marinas, entertainment venues, and mixed use projects. A successful owner does not treat every part of a property the same way. The best owners recognize that some spaces need to be repositioned, some need to be reduced, some need a different use, and some deserve additional capital because demand is already proving their value. A different Atlantic City strategy Ocean’s approach becomes even more interesting when compared with the proposed redevelopment of the Sheraton Atlantic City Convention Center Hotel. The Sheraton is a 502 room hotel directly connected to the Atlantic City Convention Center. Its owner has proposed an approximately $100 million mixed use redevelopment that would convert 130 hotel rooms into age restricted apartments while renovating 252 hotel rooms. The proposed residential component is intended to help create a more sustainable financial model for a property that the owner says cannot be supported by convention demand alone in its current form. Ocean and the Sheraton are responding to the same broad question in entirely different ways. Ocean sees a successful part of its existing operation and is investing more heavily in it. The Sheraton proposal suggests that a large convention hotel may need a different use mix, including residential income, to preserve the hospitality function that remains important to Atlantic City’s convention economy. Neither strategy is automatically right or wrong. Ocean must prove that the expanded Cove produces enough additional revenue and guest loyalty to justify its $14 million investment. The Sheraton must demonstrate that a smaller hotel and a residential component can create a durable mixed use asset without undermining the city’s ability to attract and host major conventions. But together, these properties provide an important lesson in hospitality real estate. The future is not always about adding rooms. Sometimes it is about expanding what is already working. Sometimes it is about changing the use of space that is no longer producing enough income. And sometimes the most valuable opportunity is not across town or in the next acquisition. It may be in the 10,000 square feet already inside the property you own.


